5 Financial Metrics Every Small Business Must Track (And How to Calculate Them)
If you are in a rush, here are the five financial metrics for small business you need to know:
- Gross Margin: How much you keep after direct costs (Efficiency).
- Net Margin: How much you keep after all costs (Profitability).
- Cash Runway: How many months you can survive without revenue (Safety).
- Revenue Per Employee: How efficient your team is (Productivity).
- Customer Acquisition Cost (CAC): How much you spend to get a new client (Growth).
The Psychology of Money: Why We Avoid the Numbers
Most small business owners don’t believe they are ignoring their finances. In fact, if you asked them, they would likely tell you they pay close attention.
They check their bank balance every morning while the coffee is brewing. They have a general sense of whether this month was “better” or “worse” than last month. They talk to their bookkeeper or accountant at tax time. They know if revenue is up or down.
And yet, despite this daily vigilance, many founders live with a low-level tension around money that never really goes away.
You might recognize this feeling. It’s that hesitation before you approve a new software subscription. It’s the second-guessing that happens before you hire that much-needed assistant. It’s the feeling of being incredibly busy and stressed, yet looking at the bank account and wondering, “Where did it all go?”
That tension usually isn’t about a lack of discipline. It isn’t about a lack of intelligence. And it certainly isn’t about a lack of hard work.
The problem is visibility.
Most founders are making high-stakes decisions based on “bank balance accounting” rather than true financial metrics for small business. When you don’t have clarity on what the numbers are actually telling you, every decision feels risky. Even good opportunities feel dangerous because you can’t see the road ahead.
Understanding financial metrics for small business is not about becoming a CPA or loving spreadsheets. It is about knowing which signals actually matter so you can stop guessing and start operating your company with confidence.
The “Head in the Sand” Syndrome
Before we open the dashboard, we have to talk about something most financial blogs skip entirely: Emotions.
For many founders, finances carry a heavy emotional weight. Numbers feel personal. If the numbers are bad, it feels like a judgment on your effort, your intelligence, or your worth as an entrepreneur. Because of this, many business owners subconsciously avoid digging too deeply into their financial metrics for small business.
It is a protective mechanism. If you don’t look too closely, you don’t have to confront the reality that a project lost money or that a client isn’t actually profitable.
Common thoughts that keep us in this cycle include:
- “I’m creative/visionary; I’m just not a numbers person.”
- “As long as there is money in the checking account, we’re okay.”
- “I’ll look at the P&L once things calm down next month.”
- “My accountant handles all that stuff.”
Let’s be gentle with ourselves here: running a business is hard. It is natural to want to avoid the parts that make us feel incompetent or anxious. But here is the hard truth: Avoiding your financial metrics for small business doesn’t remove risk, it hides it.
Ignorance is not bliss in business; it is a slow leak. When you track the right financial metrics for small business consistently, finances stop being a source of judgment and start becoming neutral information. The goal is not perfection. The goal is awareness.
Why Revenue Alone Is the Ultimate “Vanity Metric”
If you only look at one number, it’s probably revenue. It is the loudest number in business. It’s the one we brag about at dinner parties. “We just hit seven figures!” or “We had our best month ever!”
But revenue is also the least informative number on its own.
Relying solely on revenue is like driving a car and only looking at the speedometer. It tells you how fast you are going, but it doesn’t tell you if you have enough gas (cash flow) to get there, or if the engine is overheating (margin compression).
We see this tragic scenario play out constantly: A business doubles its revenue in a year, the founder is working 80 hours a week, the team is exhausted, and at the end of the year, there is less money in the bank than when they started.
Why does this happen? Because revenue tells you what came in. It does not tell you:
- What you kept (Profitability)
- What you can afford (Cash Flow)
- What is sustainable (Efficiency)
Many businesses with impressive top-line revenue are actually dying a slow death because their margins are shrinking, their costs are rising faster than their income, or their team is inefficient.
This is why relying on revenue alone is one of the biggest traps founders fall into. You can “grow” yourself right out of business if you aren’t watching the other key financial metrics for small business.
Metric #1: Gross Margin (The Efficiency Meter)
What is Gross Margin?
Gross margin is a financial metric that calculates the percentage of revenue your business keeps after paying the direct costs of producing your goods or services. It measures your core efficiency.
Think of it this way: If you sell a widget for $100, and it costs you $60 in materials and labor to make that widget, you have $40 left over. That $40 is your Gross Profit. The percentage (40%) is your Gross Margin.
This is arguably the most critical of all financial metrics for small business because it reveals whether your business model is fundamentally sound. If your gross margin is negative or too thin, no amount of marketing or sales will save you. In fact, selling more with a bad gross margin just helps you go broke faster.
How to Calculate Gross Margin
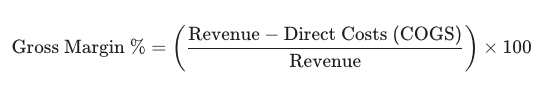
The “Direct Costs” Trap
The biggest mistake founders make here is not counting all their direct costs (often called COGS or Cost of Goods Sold). To get an accurate number, you must include:
- Materials: The physical stuff you sell.
- Direct Labor: If you run an agency, the wages of the people doing the client work are a direct cost, not an operating expense.
- Merchant Fees: The 2.9% Stripe or PayPal fee is a direct cost of that sale.
- Delivery Software: If you need a specific tool to deliver the service to the client (e.g., hosting fees), that is a direct cost.
Industry Benchmarks: Where Should You Be?
“Good” varies by industry, but here are some targets to aim for:
- Professional Services / Agencies: 50% – 70%. (You have high labor costs, but low overhead).
- SaaS / Software: 80% – 90%. (Once the code is written, selling another copy costs pennies).
- E-commerce / Retail: 30% – 50%. (You have high material and shipping costs).
- Construction / Manufacturing: 20% – 35%. (High materials and labor).
Action Plan: 3 Ways to Fix a Low Gross Margin
If you calculate this and panic because you are below the benchmark, don’t worry. This is one of the most fixable financial metrics for small business.
- Raise Prices: It sounds obvious, but a 10% price increase drops straight to the bottom line.
- Kill Scope Creep: Are you doing work for clients that you aren’t billing for? Stop giving away free inventory.
- Audit Your Suppliers: If you sell physical goods, can you negotiate better rates on materials? If you sell services, are you overpaying contractors?
Metric #2: Net Margin (The Profitability Reality Check)
What is Net Margin?
Net margin shows the percentage of revenue that remains as profit after all business expenses, including operating costs, taxes, and interest, have been paid.
While Gross Margin looks at the product, Net Margin looks at the entire company. It shows how much profit remains after everything is paid, marketing, rent, software, insurance, and yes, your salary. Among all financial metrics for small business, net margin tells the most honest story. A business can look wildly successful on the outside, fancy office, big team, slick branding, and still be financially fragile if the net margin is 2%.
How to Calculate Net Margin
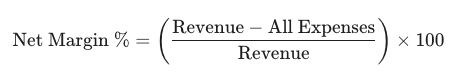
What Net Margin Reveals
Net margin is your “sleep at night” number. It tells you:
- Resilience: Can you absorb a hit? If your margin is 30%, you can lose a big client and survive. If it’s 5%, one bad month puts you in debt.
- Fuel for Growth: Net profit is what you use to reinvest in new products or hire ahead of the curve.
- Distributable Cash: This is the money that eventually ends up in your pocket as an owner’s draw or dividend.
Industry Benchmarks
- Under 10%: You are in the “Danger Zone.” You are working hard, but the business is fragile.
- 10% – 15%: This is “Average.” You are sustainable, but growth will feel slow.
- 15% – 25%: This is “Healthy.” You have breathing room.
- 25%+: This is “Best in Class.” You have a cash cow that gives you options.
Action Plan: How to Boost Net Margin
If your Gross Margin is healthy but your Net Margin is low, it means you have an “Operating Expense” problem. You are spending too much to run the business.
- The Subscription Audit: Go through your credit card statement. Cancel every software tool you haven’t used in 90 days. Most small businesses waste hundreds a month here.
- Review Staff Efficiency: Do you have a large team but low output? (We will cover this in the “Revenue Per Employee” section).
- Check Marketing ROI: Are you spending $1,000 on ads to get $1,000 in revenue? That hurts your net margin.
Metric #3: Cash Runway (The Survival Number)
What is Cash Runway?
Cash runway is a financial metric that indicates how many months a business can continue to operate with its current cash balance if all revenue were to cease immediately.
There is an old saying in business: “Revenue is vanity, profit is sanity, but cash is king.” You can have great margins on paper and still go bankrupt if you run out of cash before the client pays their invoice. This is why Cash Runway is one of the most critical financial metrics for small business for preventing bankruptcy.
How to Calculate Cash Runway
To calculate this, you first need to know your “Monthly Burn Rate.” This is simply the total amount of cash your business spends in an average month (Rent, Payroll, Software, Taxes, etc.).
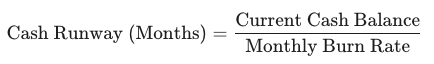
Example: If you have $50,000 in the bank and your business spends $10,000 a month to operate, you have 5 months of runway.
The “3-Month Warning”
How much runway is enough?
- Less than 1 month: You are in “Crisis Mode.” You need to secure cash immediately.
- 1 to 3 months: This is the “Caution Zone.” One bad quarter could wipe you out.
- 3 to 6 months: This is the “Safe Zone.” Most experts recommend keeping 3 to 6 months of operating expenses in the bank at all times.
- 6+ months: You are in a strong position to take risks, like launching a new product or hiring expensive talent.
Action Plan: Extending Your Runway
If your runway is too short, you have two levers to pull:
- Accelerate Inflow: Can you incentivize clients to pay upfront for a discount? Can you shorten payment terms from Net-30 to Net-15?
- Delay Outflow: Negotiate with vendors. Ask if you can pay software annually to save money, or monthly to preserve cash (depending on your specific cash need).
Metric #4: Revenue Per Employee (The Productivity Gauge)
What is Revenue Per Employee?
Revenue per employee measures the average revenue generated by each full-time equivalent employee, serving as a key indicator of productivity and team efficiency.
Revenue Per Employee is one of the most critical financial metrics for small business because labor is usually your biggest expense. If this number drops too low, it means your team is bloated, inefficient, or under-priced.
How to Calculate Revenue Per Employee
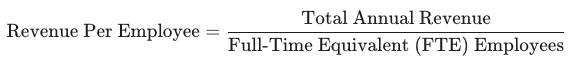
Note on FTE: If you have two part-time employees who each work 20 hours a week, they count as one Full-Time Equivalent employee.
What This Metric Tells You
- Whether to Hire: If your Revenue Per Employee is skyrocketing (e.g., $300k+), your team is likely burned out. You need to hire.
- Whether to Fire: If your number is plummeting (e.g., dropping from $150k to $75k), you have hired too fast, or your new hires aren’t productive yet.
- Whether Systems are Broken: If you add people but revenue doesn’t go up, it usually means your processes are messy.
Industry Benchmarks
- Service Business / Agency: You generally want to see $150,000 – $200,000 per employee. If you are below $100k, it is very hard to be profitable after paying decent salaries and overhead.
- Technology / SaaS: These companies often aim for $250,000+ per employee because their product scales without adding labor.
Metric #5: Customer Acquisition Cost – CAC (The Growth Metric)
What is Customer Acquisition Cost (CAC)?
Customer Acquisition Cost (CAC) is the total cost of sales and marketing efforts required to acquire a new customer.
Growth is exciting, but it can also be expensive. Without this final metric, you risk “growing broke“, acquiring new customers at a cost that actually hurts your bottom line. As your marketing spend increases, CAC becomes one of the most vital financial metrics for small business to monitor.
How to Calculate CAC
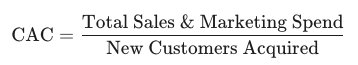
Example: In January, you spent $2,000 on Facebook ads and $3,000 on a sales rep. You acquired 10 new customers.
- Total Spend = $5,000
- New Customers = 10
- CAC = $500 per customer
The Golden Ratio: CAC vs. LTV
CAC is meaningless without context. You have to compare it to Lifetime Value (LTV), how much a customer spends with you over their entire relationship.
- The 3:1 Ratio: A healthy business generally aims for an LTV that is 3x their CAC. If you spend $500 to get a customer, they should generate at least $1,500 in value.
- The 1:1 Danger Zone: If you spend $500 to get a customer who only pays you $500, you are growing, but you aren’t making money.
Implementation: The Tech Stack & The Ritual
You don’t need a degree in finance to track these financial metrics for small business. You just need the right toolkit and a routine.
The Tech Stack
- Cloud Accounting Software: This is non-negotiable. QuickBooks Online or Xero are the industry standards. They automatically pull in your bank transactions so you don’t have to manually enter data.
- Payroll Software: Tools like Gusto make it easy to separate “Direct Labor” (people doing the work) from “Admin/Overhead” (people running the business), which is crucial for calculating accurate Gross Margins.
- The Dashboard: If you find QuickBooks confusing, consider an add-on tool like Fathom or LivePlan. These connect to your accounting software and turn boring spreadsheets into beautiful, easy-to-read charts.
The “Finance Friday” Ritual
The best dashboard in the world is useless if you never look at it. We recommend “Finance Friday.” Set a recurring calendar invite for 30 minutes every Friday morning.
- Week 1-3: Just check Cash Runway (cash balance) and Accounts Receivable (who owes you money).
- Week 4: Do the “Monthly Deep Dive.” Review all 5 financial metrics for small business.
Frequently Asked Questions (FAQ)
What are the most important financial metrics for small business?
The most important financial metrics for small business are Gross Margin (efficiency), Net Margin (profitability), Cash Runway (solvency), Revenue Per Employee (productivity), and Customer Acquisition Cost (growth).
Do I need a CFO to track financial metrics for small business?
No, not at first. A good bookkeeper can keep your records clean, and you (the owner) can interpret these 5 financial metrics for small business. You typically don’t need a Fractional CFO until you reach $1M–$2M in revenue.
How often should I check my financial metrics for small business?
You should check cash flow financial metrics for small business (like Runway) weekly, and profitability financial metrics for small business (like Gross and Net Margin) monthly. Checking them annually at tax time is too infrequent to make agile decisions.
Clarity is Confidence
You don’t need more hustle. You don’t need to grind harder. You likely just need better visibility.
The right financial metrics for small business don’t just improve your numbers, they improve your quality of life. They give you the permission to hire, the confidence to raise prices, and the peace of mind that comes from knowing exactly where you stand.
That is what operational clarity really looks like. Stop guessing, start tracking, and watch your business (and your confidence) grow.
Need help?
Related Blogs
- Bank Balance Accounting Is Lying to You (Here’s What to Track Instead)
- Founder Opportunity Cost: The Hidden $10K Monthly Loss
- Why Revenue Growth Can Make You Poorer
- From Anxiety to Authority: How Financial Visibility Changes Leadership Decisions
- Gross Margin Problems That Kill Businesses Before They Notice
- Why Your Net Margin Matters More Than Your Salary
- Pricing Fixes That Improve Profit Without Adding Clients
- Cash flow management: 7 brutal ways to stop losing profit
- How to Extend Your Cash Runway Without Panic Cuts
- The 90-Day Cash Planning Framework for Small Businesses
- Revenue Per Employee: The Metric That Tells You When to Hire (or Pause)
- Why Hiring Too Early Destroys Small Business Profitability
- Systems Before Staff: Scaling Without Payroll Panic
- Customer acquisition cost: 10 proven tips to explode profit
- The 3:1 Rule: When Growth Is Healthy and When It’s Dangerous
- Why “More Leads” Is Not a Growth Strategy
- The Finance Friday Ritual: A 30-Minute Weekly Habit That Changes Everything
- What Your Bookkeeper Tracks vs What You Must Review as the Owner
- The Small Business Financial Dashboard That Actually Gets Used
- When Small Businesses Need a Fractional CFO (And When They Don’t)
- The Difference Between Financial Data and Financial Insight
- Operational Metrics vs Financial Metrics: Why You Need Both